Prequalification vs Preapproval for an Auto Loan
Use prequalification while you are still comparing prices and monthly payments, then switch to preapproval when you are ready to buy and need stronger bargaining power, because preapproval usually means a hard inquiry and prequalification usually does not. If you handle them poorly, you can waste credit pulls or show up without a real budget. This guide compares soft-pull and hard-pull steps, credit impacts, and when each makes sense.
This guide is part of our Auto preapproval: how it works and how to get it series.
| Decision factor | Prequalification | preapproval for an auto loan | Winner |
|---|---|---|---|
| Where it fits in the process | Early browsing and budget sizing | Late-stage buying and negotiating | tie |
| Credit pull | Usually soft inquiry | Usually hard inquiry | Prequalification |
| Document burden | Often no documents; can rely on self-reported income, debts, and down payment | Prequalification and preapproval differ in how much documentation they usually involve: preapproval often calls for pay stubs, W-2s, tax returns, bank statements, and employment verification. | Prequalification |
| Estimate accuracy | Range based on self-reported details | More complete review can produce a firmer amount | preapproval for an auto loan |
| Negotiation value | Limited | Stronger, especially with a preapproval letter | preapproval for an auto loan |
| Failure risk | Can drop after verification | Can still be declined or revised if documents, DTI, or credit details change | tie |
What is the difference between prequalification and preapproval for an auto loan?
Prequalification gives you an early borrowing estimate, usually from self-reported numbers, so it is best for setting a price ceiling before you shop. Preapproval is a more formal lender review that verifies your information, usually uses a hard credit inquiry, and can support a stronger offer at the dealership.
What each step tells you
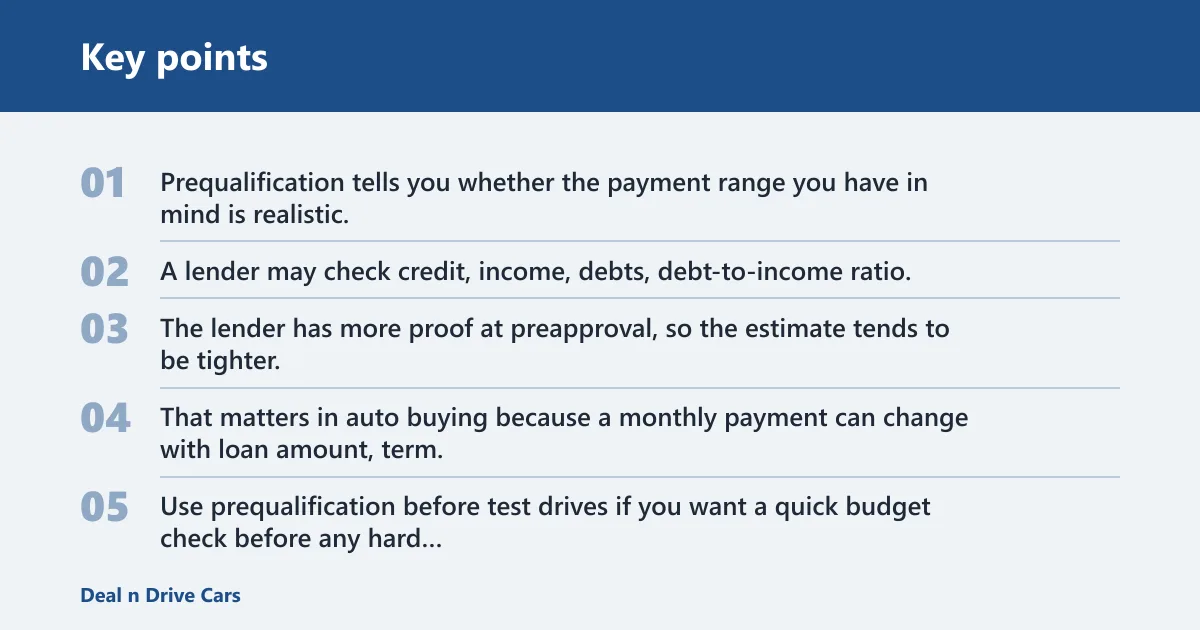
Prequalification tells you whether the payment range you have in mind is realistic. A lender may check credit, income, debts, debt-to-income ratio, and cash available for the deal during preapproval.
Why lenders treat them differently
The lender has more proof at preapproval, so the estimate tends to be tighter. That matters in auto buying because a monthly payment can change with loan amount, term, down payment, trade-in equity, and existing auto debt.
Where each one fits in the car-buying timeline
Use prequalification before test drives if you want a quick budget check before any hard inquiry. Use preapproval after you are close to a purchase, when you need a cleaner number to compare with dealer financing and stronger bargaining power.
What is prequalification for an auto loan?
Prequalification is an early estimate of borrowing power based on the numbers you give the lender. It fits shoppers who are still browsing, comparing models, and trying to keep monthly payments in range before they pick a vehicle.
Self-reported information and soft inquiry
One lender says prequalification can require no documents and uses a soft credit inquiry. It may rely on self-reported income, debts, and down payment information, which makes the step faster and easier to start.
Typical estimate range
Prequalification usually produces a range rather than a firm amount. That range can help with budgeting, but it is less accurate than preapproval because your debt-to-income ratio and other details have not been checked yet.
What it can and cannot tell you
It can tell you whether a sedan at one payment level or an SUV at another level is in play. It cannot tell you that a lender will approve the same figure after verification, and it cannot replace a final loan review.
What is preapproval for an auto loan?
Preapproval is a more formal lender review that verifies the information you provide. It is the step that makes sense when you are ready to buy, because it can give you a stronger position while you negotiate vehicle price, trade-in value, and dealer financing terms.
Verified financial information and lender review
Preapproval usually asks for income, debt, and asset details that the lender can check. That review is often more complete than prequalification and may include automated underwriting or manual lender review of the credit report and documents.
Hard inquiry and consent
One lender says preapproval uses a hard credit inquiry, while prequalification uses a soft credit inquiry. A hard inquiry can matter for credit scoring, and you should expect lender consent and more formal authorization before the review begins.
Preapproval letter and time limit
A preapproval letter can be used as proof when making an offer, and one source says it can be good for 90 days. That letter is not a final promise, but it can make your offer look more serious when you are ready to negotiate.
Does prequalification affect your credit score?
Prequalification usually uses a soft inquiry, so it is typically not scored the same way as a hard inquiry. That makes it a low-friction way to check budget, but it still depends on the lender’s process and whether you consent to a credit pull.
Soft inquiry vs hard inquiry
A soft inquiry is commonly used for early screening. A hard inquiry is generally tied to a formal credit application, and it can affect your score more than a soft pull.
Consent implications
Because prequalification is lighter, lenders often ask for less formal permission. Preapproval is different, because the lender is moving toward a lending decision and needs authorization to inspect the file more closely.
Does preapproval for an auto loan use a hard inquiry?
Yes, preapproval for an auto loan typically uses a hard inquiry. That is the trade-off for a more verified decision, since the lender is checking the file closely enough to support a stronger offer and a preapproval letter.
Why the pull matters
Hard inquiries matter because they are part of the credit application process. If you are rate-shopping, keep the number of formal applications under control so you are not stacking unnecessary pulls.
Timing matters more than the label
If you are still comparing models, a hard pull can be premature. If you are days away from signing and want a cleaner negotiation position, the hard inquiry may be worth it.
Credit pull, debt-to-income ratio, and document checks
The credit pull is only part of the difference. Lenders also look at debt-to-income ratio, income verification, and other details that can move the estimate between the first screen and the final review.
How debt-to-income ratio affects monthly payment capacity
DTI helps a lender estimate how much room you have for another payment. If your income, auto debt, or other obligations change between steps, the approved amount can change too.
Why the estimate can change
A prequalified amount can shrink after verification if the lender finds higher debt, lower income, or less stable employment than you reported. A dealer can also fail to match the rate or structure you expected, especially if the term, down payment, or vehicle price changes.
Automated underwriting and lender review
Preapproval is more complete because the lender checks documents and credit report details before giving a stronger answer. That review reduces guesswork, but it can also surface problems that a prequalification screen did not catch.
What lenders may ask for
For preapproval, lenders often want proof rather than estimates. That means pay stubs, tax returns, bank statements, W-2s, and employment verification can be part of the process, along with details about current auto debt and cash available for down payment.
Income verification
Pay stubs and W-2s help confirm current earnings. Tax returns and bank statements can help a lender verify whether your income and cash position match what you reported.
Debt, down payment, and trade-in details
A larger down payment or trade-in equity can reduce the loan amount and improve the monthly payment outlook. Existing auto debt can do the opposite by raising your obligations and pushing the DTI higher.
Employment verification
Some lenders verify employment directly, especially when the file needs more support. That extra check can matter for first-time buyers, subprime shoppers, and anyone whose income is variable or recently changed.
- Check whether you are still browsing or already ready to sign.
- Estimate your monthly payment with your likely down payment and trade-in.
- Decide whether a soft pull is enough or whether you need a stronger offer.
- Gather income and identity documents if you want preapproval.
- Compare at least two lenders before you submit the final credit application.
Prequalification vs preapproval for an auto loan decision
This matrix maps the step to your stage, credit profile, down payment or trade-in position, and dealership strategy. The best choice changes when you move from browsing to bargaining.
| Buyer stage | Credit profile | Down payment or trade-in amount | Dealership strategy | Likely credit pull | Document burden | Expected accuracy | Negotiation value | Common failure points | Best step |
|---|---|---|---|---|---|---|---|---|---|
| Early browsing, no vehicle picked | Any profile, including first-time buyers | Unknown or still changing | Set a payment ceiling before visiting lots | Soft inquiry | Low | Moderate range | Low | Self-reported debts miss a payment; range proves too high | Prequalification |
| Ready to buy within a short window | Stable credit, rate shopper, or borrower with thin file | Known cash down or trade-in value | Bring an outside offer to compare with dealer financing | Hard inquiry | High | Higher | High | Dealer cannot match terms; lender conditions change after review | preapproval for an auto loan |
| Subprime shopper with a tight budget | Higher-risk file or recent credit problems | Strong down payment helps | Find a realistic payment before visiting a dealer | Start with soft, then hard if needed | Medium to high | Range first, then tighter figure | High if negotiated carefully | Prequalified amount drops after verification; DTI fails lender limits | Both |
| First-time buyer with limited credit history | Thin or short credit file | Small to moderate cash down | Use a preapproval letter to show seriousness | Hard inquiry after screening | High | Better than prequalification alone | High | Missing income proof; lender needs more documentation than expected | preapproval for an auto loan |
Choose Prequalification if… / Choose preapproval for an auto loan if…
Choose prequalification if you are still comparing vehicles, want a soft-pull budget check, or need a fast estimate before you commit to a dealership visit. Choose preapproval for an auto loan if you are ready to buy, want a preapproval letter, need stronger bargaining power, or are rate-shopping with documents in hand.
When prequalification is enough
Prequalification is enough when you need a borrowing range, not a near-final figure. It also fits first-time buyers who want a simple starting point, or shoppers who are still deciding whether to buy now or wait.
When preapproval is worth the hard inquiry
Preapproval is worth the hard inquiry when the car hunt is serious and you need more weight at the dealership. It is also the better move if your down payment, trade-in, income, and debt picture are stable enough to verify now.
When to use both
Use both if you want a quick budget screen first and a stronger offer later. That sequence works well for rate shoppers and for buyers who want to compare lender financing against dealer financing without guessing.
Say your monthly budget is about $410 and you have about a $3,000 trade-in. Start with prequalification to see which price band fits, then move to preapproval only after you have picked the vehicle and can document income and debts.
Suppose a first-time buyer with thin credit gets a prequalified range that looks comfortable, then the verified preapproval comes in lower after DTI is checked. That is not a surprise failure; it is a sign the first number was only a rough estimate.
Frequently asked questions
Which is better for buying a car, prequalification or preapproval?
Preapproval is better when you are close to buying and want more weight with the dealer. Prequalification is better when you are still shopping and need a quick budget check. If you are rate-shopping, many buyers use prequalification first and preapproval later.
Can I shop for rates with a prequalification first?
Yes, and that is often the smarter order. Prequalification lets you compare lender ideas without much friction, then you can decide which offer is worth a formal application. That helps you avoid unnecessary hard pulls while you are still browsing.
What should I do if prequalification and preapproval amounts are different?
Start with the verified number, not the softer one. A lower preapproval can mean your DTI, income, debts, or down payment assumptions changed under review. If the gap is large, revisit the vehicle price, loan term, or trade-in plan before signing.