Can You Get a Car Insurance Quote Without a VIN or Registration?
Many insurers can quote a car without a VIN or registration if given the year, make, model, trim, mileage, ZIP code, and driver details. The price typically stays provisional until the insurer verifies the VIN. If the VIN later changes the trim, equipment, or theft profile, your final premium can move. This guide explains what insurers can price now, what stays uncertain, and how to spot a surprise before you buy.
What insurers price without a VIN
Yes. In many quote flows, an insurer can start with year, make, model, trim, ZIP code, and driver profile, then tighten the estimate later with the VIN. That gives you a usable shopping quote, but not a final rate. The closer those details match the exact vehicle, the better the estimate tends to be.
What insurers can price from basic vehicle details
Without a VIN, insurers can still price the main parts of a policy from the car description and your driver information. They can estimate liability and often add comprehensive and collision using the vehicle’s age, trim, and local pricing factors. Progressive says liability coverage is required for all drivers in most states, and GEICO says liability coverage is required in most states.
ZIP code matters because it feeds local loss patterns, state rules, repair costs, and theft risk. Driver age, driving history, prior insurance, annual mileage, and whether the car will be owned outright, financed, or leased can all influence the quote before the VIN is provided.
Why the result is an estimate, not a final rate
The VIN identifies the exact vehicle. It lets an insurer verify specs, history, anti-theft equipment, and risk details that may not show up in a broad trim label. That is why a pre-VIN quote can be close, but still miss details that change price.
Suppose you enter a 2019 Honda CR-V EX-L, but the vehicle is actually an EX-L with a factory towing package and a different wheel package. The insurer may price one version first, then change the quote after the VIN shows the exact build. The same can happen with theft risk, safety equipment, or a trim that is easy to confuse on a dealer listing.
Why insurers ask for the VIN
Insurers ask for the VIN because it pins the policy to one exact car. It helps with rating accuracy, history checks, and fraud prevention. It is also the piece most carriers use before final policy issuance, because it confirms the vehicle being insured is the one being rated.
Exact vehicle identification
The VIN can reveal details that a shopping listing often omits or gets wrong. That includes exact trim, engine, drivetrain, body style, factory equipment, and sometimes safety or anti-theft features. If the quote was built from an assumed trim, the VIN can correct it.
History checks and fraud prevention
Insurers use the VIN to look for history signals that may affect coverage or price, including title status and other vehicle records. That matters because two cars with the same year and model can have very different underwriting outcomes if one has a salvage title, a prior loss, or altered equipment.
Why the final policy often needs it
Registration is not the same gatekeeper as the VIN. Registration helps confirm ownership or use in some steps, but the VIN is usually the key identifier for the vehicle itself. You may start a quote without registration, then be asked for the VIN before binding coverage or finishing paperwork.
What to enter instead of a VIN
If the VIN is missing, enter the most exact vehicle details you have. Year, make, model, trim, engine, drivetrain, and body style are the best substitutes. Then pair those details with your ZIP code, driving record, annual mileage, and coverage choices so the quote reflects the way the car will actually be used.
Vehicle details that matter most
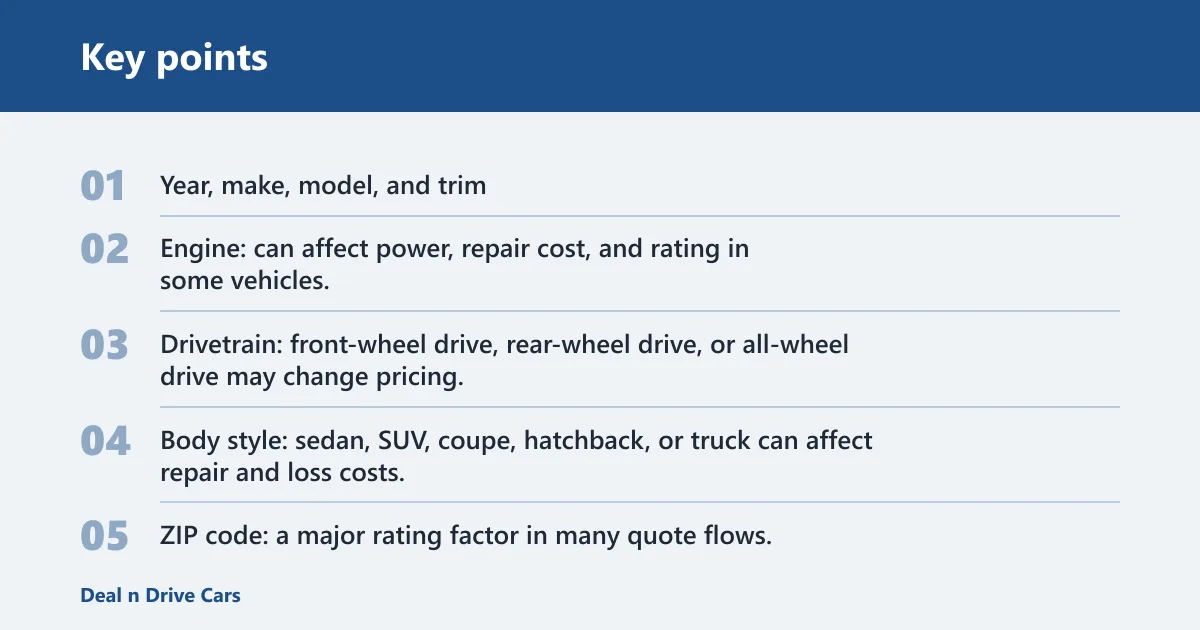
- Year, make, model, and trim: the core identifiers for a temporary estimate.
- Engine: can affect power, repair cost, and rating in some vehicles.
- Drivetrain: front-wheel drive, rear-wheel drive, or all-wheel drive may change pricing.
- Body style: sedan, SUV, coupe, hatchback, or truck can affect repair and loss costs.
- ZIP code: a major rating factor in many quote flows.
Driver and policy details that still move price
Driver profile is still a major input. Age, driving history, location, and coverage needs can move the quote more than a small trim difference in some cases. Annual mileage matters too, since a commuter who drives 18,000 miles a year usually presents a different risk than someone who drives 6,000.
Coverage level also matters. Liability is the base in most states, while comprehensive and collision add protection for losses to the car itself. The same source says comprehensive and collision are often purchased together for a new car or high-value vehicle. GEICO says collision covers damage when your car hits, or is hit by another vehicle or object, and comprehensive may pay for losses from theft, vandalism, or weather events. The same source says comprehensive covers theft, fire, hail damage, other acts of nature, vandalism, and theft.
How to compare quotes on the same basis
Match the deductible and coverage limits before comparing prices. The same source says a deductible is the amount you pay out of pocket before coverage applies, and a higher deductible may lower your premium. Coverage limits also matter because a quote with 25/50/25 is not comparable to one with 100/300/50. If one quote has a higher deductible or lower limits, it is not a like-for-like comparison.
- Gather the vehicle’s year, make, model, trim, engine, and drivetrain.
- Enter the correct ZIP code where the car will be garaged.
- Use the primary driver’s age, record, and annual mileage.
- Select the same liability limits, deductible, and optional coverages on every quote.
- Recheck the quote after the VIN is added before you bind coverage.
Can I insure a car before registering it?
Often, yes. You can usually start or even bind coverage before registration if you have the vehicle details and enough buyer information. Registration is not always required at the quoting stage, but it may be needed later to complete paperwork, prove ownership, or satisfy state steps after the sale.
When registration is not needed yet
If you are buying a used car and need proof of insurance for the sale, many insurers can work from the VIN or, if that is missing, from year, make, model, and trim. A dealer sale, a private-party purchase, or a vehicle in transit can all start with an estimate before the registration paperwork is complete.
When registration may be required later
Some states and lenders want registration or title details before the policy is fully active or the paperwork is finalized. If the vehicle is financed or leased, the lender may also require comprehensive and collision. That can change the premium after the VIN is added and the ownership details are confirmed.
Buying before delivery or title transfer
Picture a shopper who agrees to buy a sedan on Friday but will not get the title until Monday. The insurer can often quote the car before the title transfer, then update the policy once the VIN and ownership details are verified. That avoids a dead stop during the purchase, but it does not make the first estimate final.
How accurate is a quote without the exact vehicle?
It can be close, but it can also move enough to matter. Accuracy is best when the trim, drivetrain, and equipment are clear and the vehicle is common. It is weaker when the listing is vague, the car is unusual, or the car’s history and equipment are likely to change the comp and theft profile.
The inputs that most often change the price
The biggest shifts usually come from exact trim, drivetrain, engine, annual mileage, garaging ZIP, driver profile, prior insurance, lien or lease status, safety features, and coverage level. Those are the same items that can change a quote even after the VIN is added, because they affect how the insurer rates the risk.
| Input | What a pre-VIN quote can use | What can change later | Risk of final-price change |
|---|---|---|---|
| Exact trim | Dealer listing or seller description | Feature content, repair cost, theft profile | High |
| Drivetrain | Listed FWD, RWD, AWD, or 4WD | Incorrect or missing drivetrain detail | Medium |
| Engine | Estimated from trim | Different engine option than expected | Medium |
| Annual mileage | Your estimate | Commuting distance or usage pattern | Medium |
| Garaging ZIP | Your current ZIP code | Where the car is actually kept | High |
| Driver profile | Age and driving history | Violations, claims, or household changes | High |
| Prior insurance | Continuous coverage or lapse | Gap in coverage or no prior policy | Medium |
| Lien or lease status | Own, finance, or lease | Lender-required coverages | High |
| Safety features | Known from the listing | VIN reveals missing or extra features | Medium |
| Coverage level | Liability, comprehensive, collision, limits, deductible | Quote becomes a different policy if changed | High |
When the estimate is least reliable
Imported vehicles, salvage titles, dealer stock with missing paperwork, and cars with mismatched trim are the biggest warning signs. A quote built from a listing alone can miss an import-specific part, a branded title, or equipment that is not present on the actual car. That is where the VIN can shift the price more sharply.
A common mistake is assuming a quote can’t be started until the vehicle’s VIN and registration are in hand, even when the car is still being purchased. Suppose the dealer lists a 2021 Toyota RAV4, but the car is actually a hybrid XSE with a different drivetrain and extra equipment. The first quote may look fine, then move after the VIN confirms the exact build.
VIN quote checklist
Use this checklist to judge whether a no-VIN estimate deserves low, medium, or high confidence. The more exact the inputs, the less likely the final premium is to swing. This does not make the quote binding; it just tells you how much trust to place in the estimate.
| Input | Have it? | Effect on estimate |
|---|---|---|
| Exact trim | Yes / No | Highest impact when missing |
| Drivetrain | Yes / No | Can change equipment and repair pricing |
| Engine | Yes / No | Can alter rating on some models |
| Annual mileage | Exact estimate / rough guess | More exact means better pricing |
| Garaging ZIP | Exact ZIP / move pending | Wrong ZIP can distort local pricing |
| Driver profile | Age, record, household use | Major rating factor either way |
| Prior insurance | Continuous / gap / none | Can move underwriting result |
| Lien or lease status | Own / finance / lease | Can force additional coverage |
| Safety features | Known / uncertain | VIN may confirm missing features |
| Coverage level | Limits and deductible fixed | Must match across quotes |
Confidence labels
High confidence: you know the exact trim, drivetrain, engine, ZIP code, mileage, and coverage choices, and the car is a standard U.S. model with no title or equipment surprises. A VIN can still move the quote, but usually by a smaller amount.
Medium confidence: most details are known, but one or two items are estimated, such as mileage or equipment. That is common when you are comparing a few used cars and have not seen the final paperwork yet.
Low confidence: the listing is vague, the trim is unclear, the car may be imported or branded, or the paperwork is incomplete. Expect a larger gap when the VIN is added.
What to watch for with used cars
Used-car shopping is where no-VIN quotes help most, but also where errors are easiest to make. If you are comparing several cars, each one needs its own estimate because trim, drivetrain, and title status can differ even within the same model year. One quote is not enough for several different vehicles.
Multiple vehicles, one estimate
If you are comparing three SUVs, run three separate quotes. A base model, midtrim, and top trim can price differently, especially once comprehensive and collision are added. Keep the same driver profile and coverage limits for each one so the comparison stays clean.
Imported, salvage, or mismatched-trim cars
These cars need extra caution. Imported vehicles can have parts or equipment that are not obvious from the listing. Salvage titles can change underwriting. Mismatched trim is common in dealer stock when a listing uses the wrong package or omits factory options.
When to recheck before you bind
Recheck the quote when the VIN arrives, before you accept the deal or send payment. That is the moment when exact trim, equipment, and history can change the premium. If the price jumps, compare the revised quote with another insurer using the same deductible and limits.
Frequently asked questions
Can you get a car insurance quote without a VIN?
Yes. Many insurers can start a quote with the year, make, model, trim, ZIP code, and driver details. That estimate is temporary until the VIN is added, because the VIN confirms the exact vehicle and can change the pricing of trim, equipment, and history-based risk.
Can I get a car insurance quote before buying the car?
Yes. That is one of the main reasons pre-VIN quoting exists. You can estimate the premium before you sign, compare several used cars, and see whether a better-equipped trim will push the cost outside your budget. Treat the first number as a shopping estimate.
What information do I need for a quote if I don’t have the VIN?
You should have the year, make, model, trim, engine, drivetrain, body style, ZIP code, driver age, driving history, annual mileage, prior insurance status, lien or lease status, and the coverage level you want. The more exact those inputs are, the better the estimate usually tracks the final premium.
Will my insurance quote change after I add the VIN?
It can. The biggest changes often come from exact trim, safety equipment, theft risk, prior title issues, and any mismatch between the listing and the real car. If the VIN confirms the vehicle is different from the description, the final premium may move enough to matter.
How accurate is an insurance estimate without the exact vehicle?
Accuracy ranges from fairly close to materially off. It is better when the trim and equipment are clear and the vehicle is ordinary, and worse when the listing is vague, the car is imported, or the title status is uncertain. A no-VIN quote should guide shopping, not settle the final price.