How Does Auto Loan Preapproval Work?
Auto loan preapproval is a lender’s conditional yes after reviewing your credit, income, and basic identity data, and it may provide an estimated rate, term, and borrowing limit for roughly 30 to 60 days. Without it, you can waste time on cars you cannot fund or accept a worse deal at signing. This guide explains the lender workflow, what changes at final approval, and the decision points that matter for used-car, online-lender, and weaker-credit shoppers.
This guide is part of our Auto preapproval: how it works and how to get it series.
What auto loan preapproval means
Conditional approval before final financing
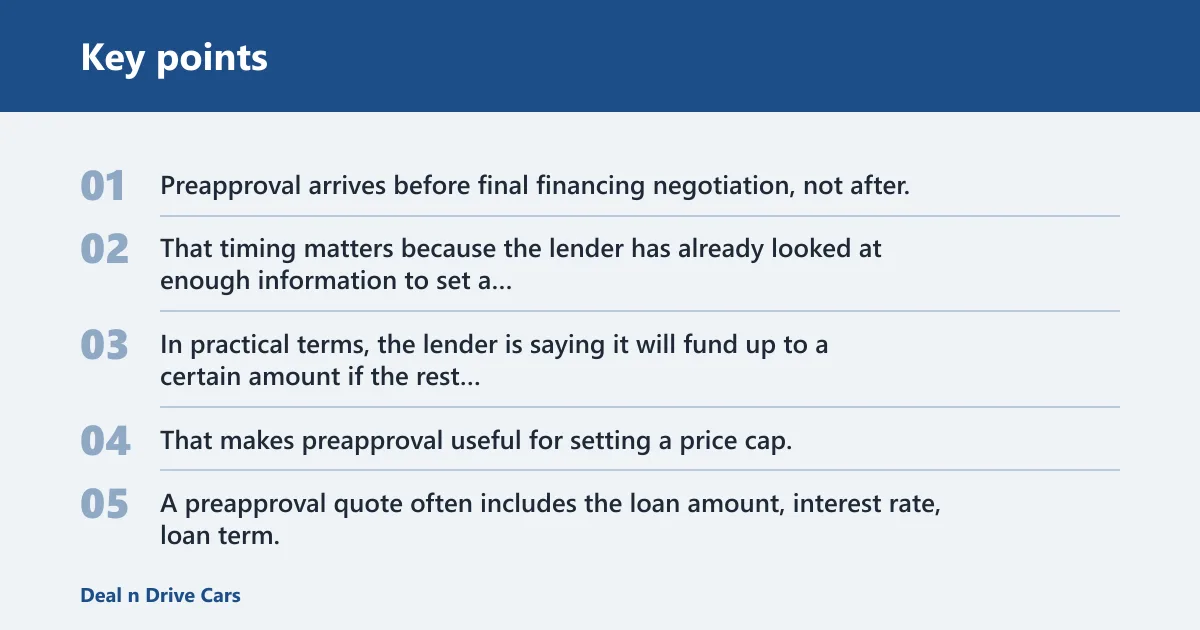
Preapproval arrives before final financing negotiation, not after. That timing matters because the lender has already looked at enough information to set a tentative offer, but the loan is still conditional until the vehicle, contract, and final underwriting all line up.
In practical terms, the lender is saying it will fund up to a certain amount if the rest of the file matches what was reviewed. That makes preapproval useful for setting a price cap, but it is not the same as a finished loan contract.
What a preapproval letter usually includes
A preapproval quote often includes the loan amount, interest rate, loan term, estimated monthly payment, and expiration date. Those details let you compare offers side by side and see how the term changes both the payment and the total interest you will pay.
The monthly payment is not a side note. It is part of the affordability check, and it should help you decide what price range fits before you spend time on a vehicle that stretches it too far.
How lenders use it to set a budget
Preapproval helps shoppers set a realistic price cap and narrow vehicles to that range. It can also strengthen your position because you can compare the dealer’s financing offer with the lender’s quoted terms instead of guessing which one is better.
Say your lender preapproves $28,000 at a stated term and rate, but the cars on your list all land near $34,000 after taxes and fees. That gap is useful before you reach the showroom, because it tells you to adjust the search or bring more cash to the deal.
How the lender workflow usually works
The lender process usually starts with an application, moves through credit and income review, then ends with conditional terms and a deadline. Final funding happens later, after the vehicle and contract details match what the lender approved.
Application and identity checks
You start by submitting identity, income, residence, and contact information. Some lenders also ask for vehicle details if you already have a car in mind, especially when the loan is tied to a specific used vehicle.
That first review is often automated or partially automated. It is designed to confirm who you are, how much you earn, and whether the loan amount appears consistent with your stated budget.
Credit review and income review
A lender may use a soft credit pull for an early screen, which generally does not show as a hard inquiry. A hard credit pull may also occur during preapproval, and that hard check typically appears on your credit history. The lender should disclose which type it will use.
Income review helps the lender judge whether the monthly payment fits your profile. That is why a preapproval is more than a credit score check; it is a lending decision built around repayment ability as well as credit history.
Conditional terms and expiration date
The lender then issues conditional terms, usually including rate, term, and loan amount, along with a deadline. Preapprovals have time limits, so the purchase should happen before the deadline or the lender may recheck the file and change the terms. (Caranddriver)
That deadline matters at busy dealerships. A car can sell while you are comparing options, and a stale preapproval may no longer match current rates, your updated income, or the vehicle you finally choose.
Preapproval walkthrough matrix
This table shows the lender workflow from application to funding, plus how each step can matter at the dealership.
| Application step | Dealership use case | Lender action | Buyer sees what | Documents usually requested | Likely credit pull | What can still change before funding |
|---|---|---|---|---|---|---|
| Initial application | Use it to start comparing outside financing before visiting the sales desk. | Collects basic identity and loan request details. | An online form or branch application confirmation. | Legal name, address, income, employer, contact details. | Soft pull or hard pull, depending on lender policy. | Requested amount, term, and whether the file moves to full review. |
| Credit review | Lets you know whether dealer financing has a realistic benchmark to beat. | Reviews credit history and borrowing amount. | A pending status or a request for more information. | Sometimes recent pay stubs or bank statements. | May involve a hard credit pull. | Rate, approved amount, or denial if the profile does not fit. |
| Income and affordability review | Helps you judge whether a dealer payment quote is actually affordable. | Checks monthly payment against income and debt load. | Conditional approval with an estimated payment. | Proof of income, residence, and possibly debts. | Usually already decided by this stage. | Monthly payment estimate, loan amount, or required down payment. |
| Conditional approval issued | Use the letter to compare lender financing with dealer financing. | Sets loan amount, interest rate, loan term, and deadline. | A preapproval letter or quote. | Vehicle details may be requested later. | Not always repeated. | Vehicle eligibility, final APR, and deadline compliance. |
| Vehicle chosen | Shows whether the car fits the lender’s rules and your budget. | Reviews the exact vehicle, price, and contract details. | Dealer worksheet or buyer’s order. | VIN, purchase price, taxes, fees, down payment. | Usually no new pull unless the lender rechecks. | Approved amount if the car price, mileage, or age changes. |
| Final funding | Determines whether to use the lender, dealer financing, or neither. | Closes the loan and sends funds after final underwriting. | Final contract and delivery paperwork. | Signed sales contract, title docs, insurance proof if required. | May include a final verification pull in some cases. | Anything that changes income, credit, vehicle condition, or down payment before closing. |
How prequalification differs from preapproval
Prequalification is a lighter review than preapproval. It is described as a short skim of your credit history and borrowing amount, and some lenders use the terms interchangeably. Ask which process you are getting so you know how much weight to place on the result.
Lighter review and faster screen
Prequalification can be a quick way to estimate a budget, but it is less detailed than preapproval. Because it may rely on a shorter credit review, it can be useful early in shopping when you are still sorting out price ranges.
Why some lenders use the terms loosely
Some lenders use prequalification and preapproval interchangeably, but that does not make them identical in every case. One lender may issue a soft-pull estimate, while another may treat the same wording as a stronger conditional approval with more documentation attached.
When to ask for the exact process
Ask whether the review is a soft pull or a hard pull, whether the quote includes a deadline, and whether the lender intends to do a deeper review later. Those three answers tell you whether the offer is a loose screen or a stronger step toward funding.
Picture a shopper with a 640 score who wants a used compact SUV. A quick prequalification may say the payment looks workable, but a full preapproval can still tighten the loan amount, set the term, and expose missing documents before the buyer signs anything at the dealership.
What happens at the dealership after preapproval?
After preapproval, the offer becomes a benchmark. You can compare dealer financing against it, check whether the dealer can match the rate or improve the structure, and decide which lender offer fits the vehicle, payment, and timing best.
Using the offer as a benchmark
The preapproval letter gives you concrete numbers to work with. That helps the salesperson and finance office see that you are not guessing about your budget, which can narrow the conversation to the car and the contract instead of restarting the loan search from zero.
Comparing dealer financing with the lender offer
At the dealership, the key comparison is not just the payment. Look at interest rate, loan term, total finance charge, required down payment, and any add-ons that change the final amount due.
Dealer financing can be worth considering if it beats your preapproval, but do not assume that a lower payment means a better deal. A longer term can lower the monthly bill while increasing total interest.
What can change before final funding?
Final funding can still shift if income changes, the vehicle details change, the down payment changes, or the credit profile changes before underwriting closes. A new late payment, a new loan, or a different car can all affect the final terms.
A common buyer mistake is assuming a preapproval guarantees the same loan amount even after a job change or new debt appears. It does not. The lender still has to verify the car, the contract, and the final numbers before sending money.
Does auto loan preapproval hurt your credit?
Auto loan preapproval can affect credit depending on the lender’s review method. A hard credit pull may occur during preapproval and will show on your credit history, while a soft credit pull does not show as a hard inquiry. Ask before you apply.
Hard pull versus soft pull
A hard inquiry can appear on your credit report and may matter if you are applying for several loans at once. A soft pull is less invasive and is often used for an early review, but it may not be enough for a final preapproval offer.
How rate shopping can affect inquiries
Multiple preapproval applications during rate shopping can create several credit inquiries, so timing can matter. Some scoring models treat similar auto inquiries made within a short window more gently, but you should still keep applications grouped and limited.
What to confirm before you apply
Before you submit, confirm whether the lender will use a soft pull or a hard pull, whether the quote can change later, and whether the preapproval will require another review at the dealership. That keeps the credit impact and timing clear.
How long does a preapproval last?
Auto loan preapprovals have time limits, and the deadline varies by lender. The purchase should happen before that deadline because the lender may recheck the file, refresh the credit review, or change the rate, term, or amount if the quote expires.
Typical deadline and expiration
A preapproval deadline tells you how long the lender will honor the quoted terms. Once that date passes, the offer may no longer be valid, especially if market rates move or your financial profile changes.
Why timing matters for the purchase
Timing matters because vehicle availability and financing timing are linked. If the right car appears near the end of the deadline, you may need to move quickly or ask the lender whether the quote can be extended.
What happens if the quote expires
If the quote expires, the lender may ask for updated documents or run a fresh review. That can change the amount, the rate, or both, so do not treat an expired preapproval like a live offer.
Frequently asked questions
How does auto loan preapproval work?
You submit an application, the lender reviews your credit, income, and identity, and then issues a conditional approval with a loan amount, rate, term, and deadline. That quote is used before final financing negotiation, then rechecked before funding if the vehicle or your file changes.
How does auto loan prequalification work?
Prequalification is usually a short skim of your credit history and borrowing amount. It can be faster and lighter than preapproval, and some lenders use the terms interchangeably, so ask whether the review is only an estimate or a stronger conditional offer.
What happens when you are preapproved for a car loan?
You can shop with a set price cap, compare dealer financing against the lender offer, and decide whether the car fits the payment and term. The loan is still conditional, so final funding depends on the vehicle, contract, and any updated verification.
Does getting preapproved for an auto loan hurt your credit?
It can, if the lender uses a hard credit pull during preapproval. That hard check will show up on your credit history. A soft pull does not show as a hard inquiry, so ask which type the lender plans to use before you apply.
Can you get auto loan preapproval without a hard inquiry?
Sometimes. A lender may use a soft credit pull for an initial review, but not every lender does, and some will later run a hard pull before final approval. The lender should disclose the inquiry type up front so you can compare offers without surprises.